Should I Add A Second Income Stream?

Everything you read says diversify, and the reasoning is sound: one income is one point of failure. So a second thing gets started, and then a third, and eighteen months later there are three half-built projects and the main income has stopped growing because nobody was tending it. The advice was not wrong. It was simply missing the part about timing, which is what a read on your own income first supplies.
The quick answer
It is not really “one income or several.” It comes down to one thing: whether your main income is still climbing. While it is, deepening it usually beats starting something new, because you are adding to something that already works. Once it flattens, or if it depends on a single client or employer, the second stream stops being a distraction and starts being insurance. Checking which of those two you are in takes minutes.
Below: the thing that decides it, a quick table for your own situation, and the two opposite risks that make this argument so hard to settle.
It is not really focus against diversifying
Both sides are describing a real disaster. One person lost a single client that was most of their income and will tell you never to depend on one thing again. Another spread themselves across four projects, did all of them adequately and none of them well, and will tell you focus is everything. Both learned something true, and neither is describing the state your income is currently in – which is why starting from your own two years settles it faster than either story.
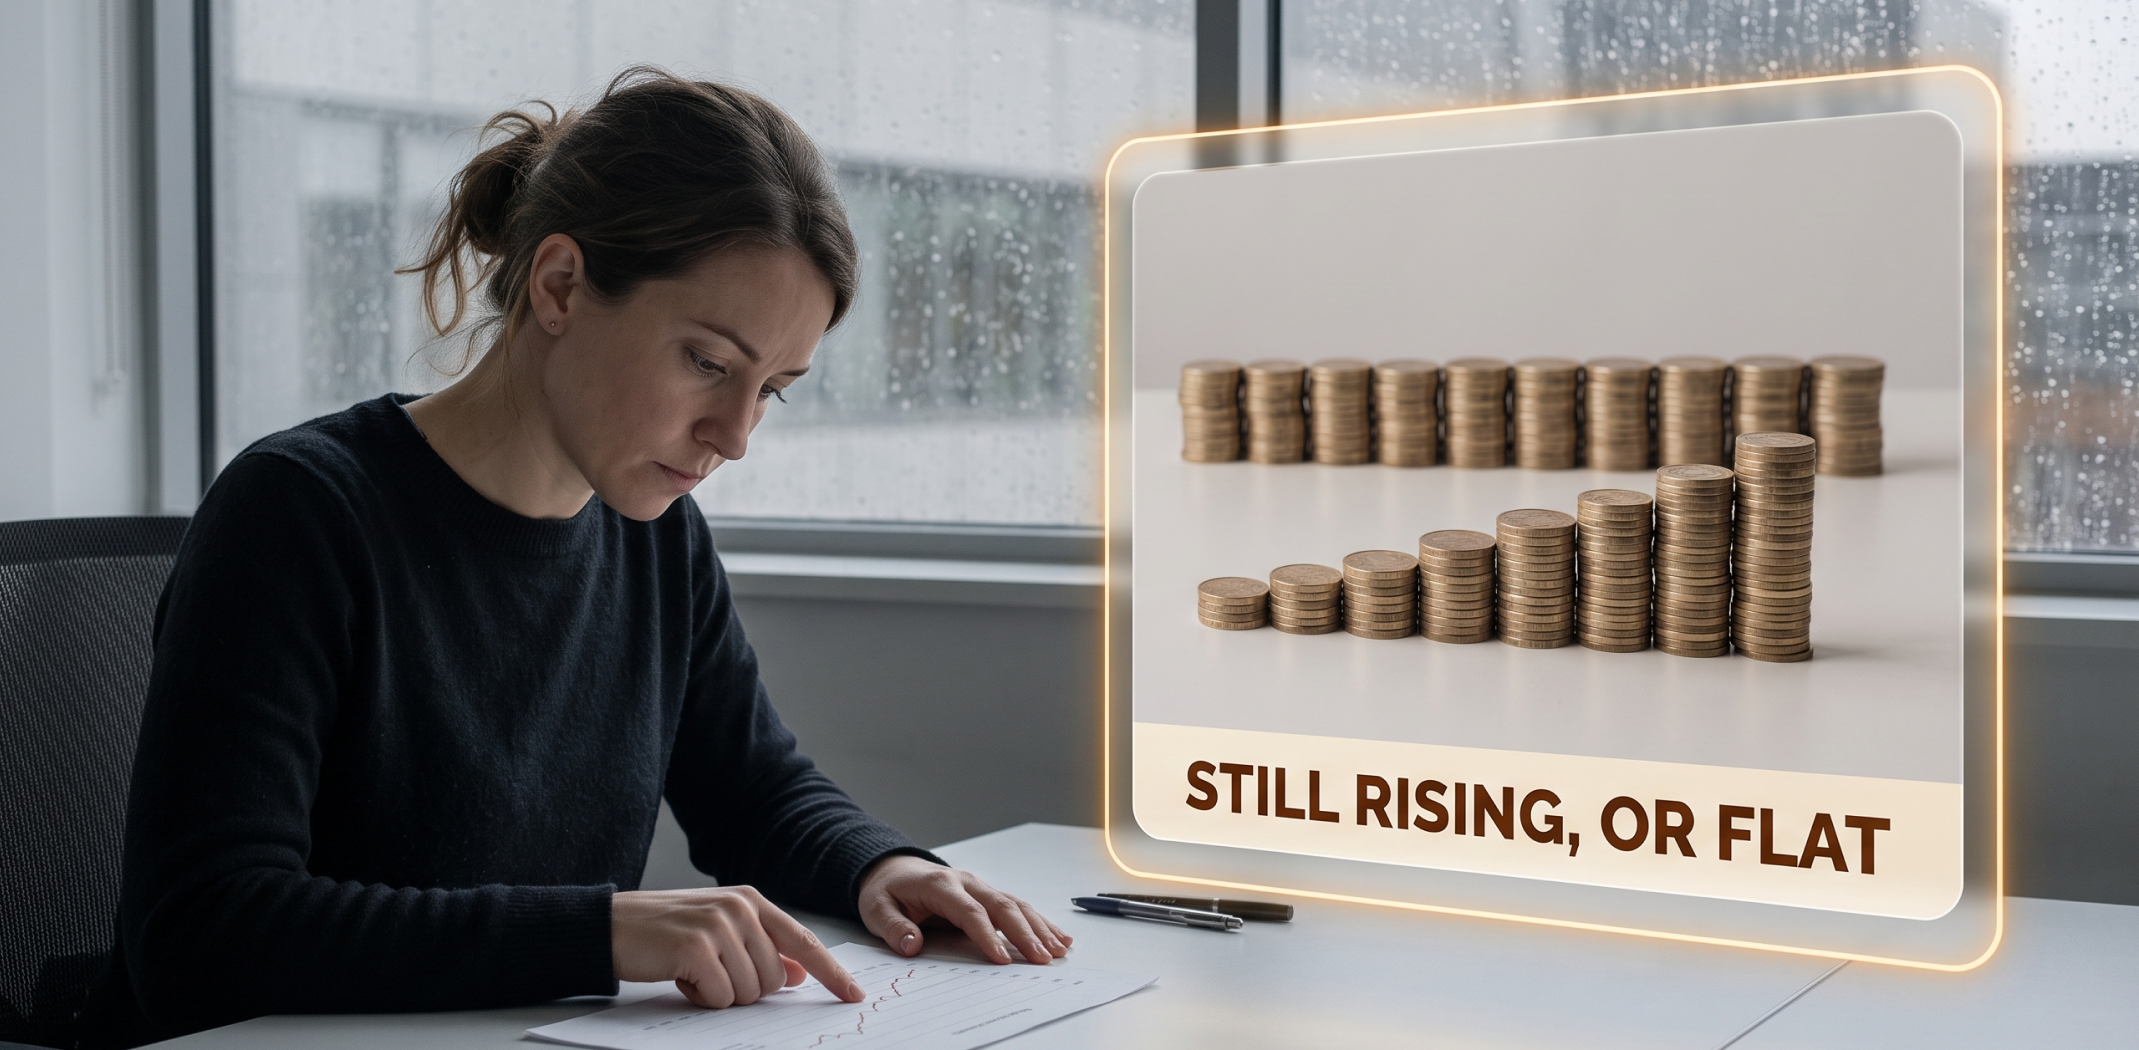
The mechanism is worth setting out. There are two opposite risks here, and almost nobody weighs them together. Concentration risk is losing everything at once when a single source disappears. Dilution risk is that two half-finished streams together earn less than one finished one, because most income takes a while before it repays the effort. Weighing both risks against your own income is what turns this from a debate into a decision.
So the question is not whether diversifying is wise in general. It is which of the two risks is currently larger for you, and that changes as your main income changes.
Match the move to your main income
Look at what your main income did over the last two years and how many places it comes from, then find yourself in the table. Sorting that honestly takes a few minutes and usually settles the timing question.
| Your main income | What usually works | Why |
|---|---|---|
| Still climbing, several clients | Deepen it, and wait | Adding now dilutes something that is working |
| Still climbing, one client or employer | Add a small second stream | The growth is real and so is the single point of failure |
| Flat for a year or more | Add, and choose deliberately | Deepening has stopped paying, which is the signal |
| Falling, or a contract ending | Add urgently, protect the main one | This is the situation the advice was written for |
Treat those as a starting point rather than a rule. How replaceable your main income would be, how much notice you would get, whether your field is contracting and how many hours you genuinely have all move the line, which is why the answer belongs to your situation.
If you are adding, add one thing
Here is the part people miss: the failure mode of diversifying is almost never choosing the wrong stream. It is choosing three at once. Each new source has a stretch at the beginning where it costs hours and returns nothing, and running three of those simultaneously is how eighteen months disappear. Sequencing them instead of stacking them is the whole difference.
A second stream that survives tends to have three properties.
A second stream worth starting · three tests
It fails for different reasons than the first. A second client in the same industry is not diversification. If one recession takes out both, you have doubled the work and kept the risk.
It uses something you already have. A skill, a tool, an audience, an existing set of contacts. Starting from nothing is what makes the unpaid stretch long enough to abandon.
It has a size and an end date for the test. Three months, or twenty hours, decided in advance. Without that, a stream that is not working quietly continues consuming the time your main income needed.
Different failure, existing assets, a bounded test. One at a time, and the next one only after this one stands up.
Notice that none of this argues against having several incomes eventually. It argues about order, and a plan that builds them in sequence exists so the first one is finished before the second one starts.
What adding too early really costs
It costs the main income. Attention is the input that grows any established source, and it is the only input you cannot buy more of. Take a third of it away during the years when the first income was still compounding and you have traded a known return for an unknown one.
The reverse mistake is worse when it lands, which is why the advice exists at all. A single client or employer disappearing takes the whole income at once and rarely gives notice. So: check whether your main income is still growing, count how many places it comes from, then either deepen it or add one thing deliberately. A plan that names which risk you are carrying is what makes that a decision rather than a reflex.
Focus vs stack everything vs sequence it
You can work this out yourself, for free, with two years of records and an evening. Here is how the usual approaches compare with sequencing streams deliberately.
| Way to decide | Cost | Built on your own risk? | Time |
|---|---|---|---|
| Focus and hope | Free | No – ignores concentration risk | Fine until it is not |
| Start three things at once | Free | No – three unpaid stretches at once | Usually abandoned |
| A business coach | $100–250/hr | Sometimes – costly before the second stream earns | Ongoing |
| Income Diversification Planner | $39 | Yes – your risk, your assets, one at a time | About 15 min |
“Is waiting not just an excuse to avoid starting?” Sometimes it genuinely is, and that deserves saying plainly rather than letting timing become a permanent reason to do nothing. The difference is whether you can name the condition that would change your answer. “When my main income stops growing” or “when this contract ends” is a plan. “When things settle down” is a way of never starting, and a year from now the situation will look identical. This is general educational guidance rather than business or financial advice, and outcomes vary considerably with your field and effort.
If it still sounds like hedging, two people faced the same choice from opposite ends of it.
Two people, two opposite errors
One added four things while the first was still growing. The other refused to add anything until the decision was made for him.
“Four projects in a year, all of them at the beginning stage, and my actual income fell because nobody was looking after it. Finishing one before starting the next was the only thing that changed.”
Solveig R. · translator, Fort Collins CO
“One builder was almost everything I earned and I kept saying I would sort it out after the busy season. The busy season ended when they did, and I would rather have started the second thing while I still had a choice.”
Boniface A. · cabinet installer, Erie PA
Several income sources arriving on different schedules makes a month harder to predict, and the Irregular Income Budget Plan is built for exactly that. Results vary; this is general guidance rather than business or financial advice.
Five short answers, and a read on your own situation comes back the same day: whether your main income is still growing, how exposed it is to a single client or employer, and which of the two risks is currently the larger one for you. If the answer is to add something, it comes back as one stream rather than four, built from what you already have and with an end date on the test. The order is the part that decides whether any of it survives.
*Individual results may vary.
Should I add a second income stream or grow the one I have?
What are the two risks being weighed?
Why is starting several streams at once a problem?
What makes a good second stream?
How do I know if I am just avoiding starting?
Is this business advice?


Recommended for You