Savings Challenge Or Automatic Transfer?

Every January the same two suggestions arrive. Run a savings challenge, because watching the number climb keeps you going. Or set up an automatic transfer and stop thinking about it, because willpower is not a plan. Both come from people who saved successfully, both are honest advice, and the reason they disagree is that they are describing two different kinds of paycheck.
The quick answer
It is not really “challenge or autopay.” It comes down to one thing: how steady your income is week to week. A rising challenge asks for its largest deposits at the end, which for most people lands in the most expensive months of the year. A flat transfer asks the same amount every time and never chooses a bad week to get ambitious. Checking your worst week against the biggest deposit settles it in minutes.
Below: the number that decides it, a quick table for your own income, and why most challenges break in the same month every year.
It is not really challenge against autopay
Both sides are arguing from experience. One person finished a challenge and remembers the momentum: the chart on the fridge, the satisfaction of a week ticked off. Another set up a transfer years ago and has not thought about it since. Neither is wrong about themselves, and neither is describing your income.
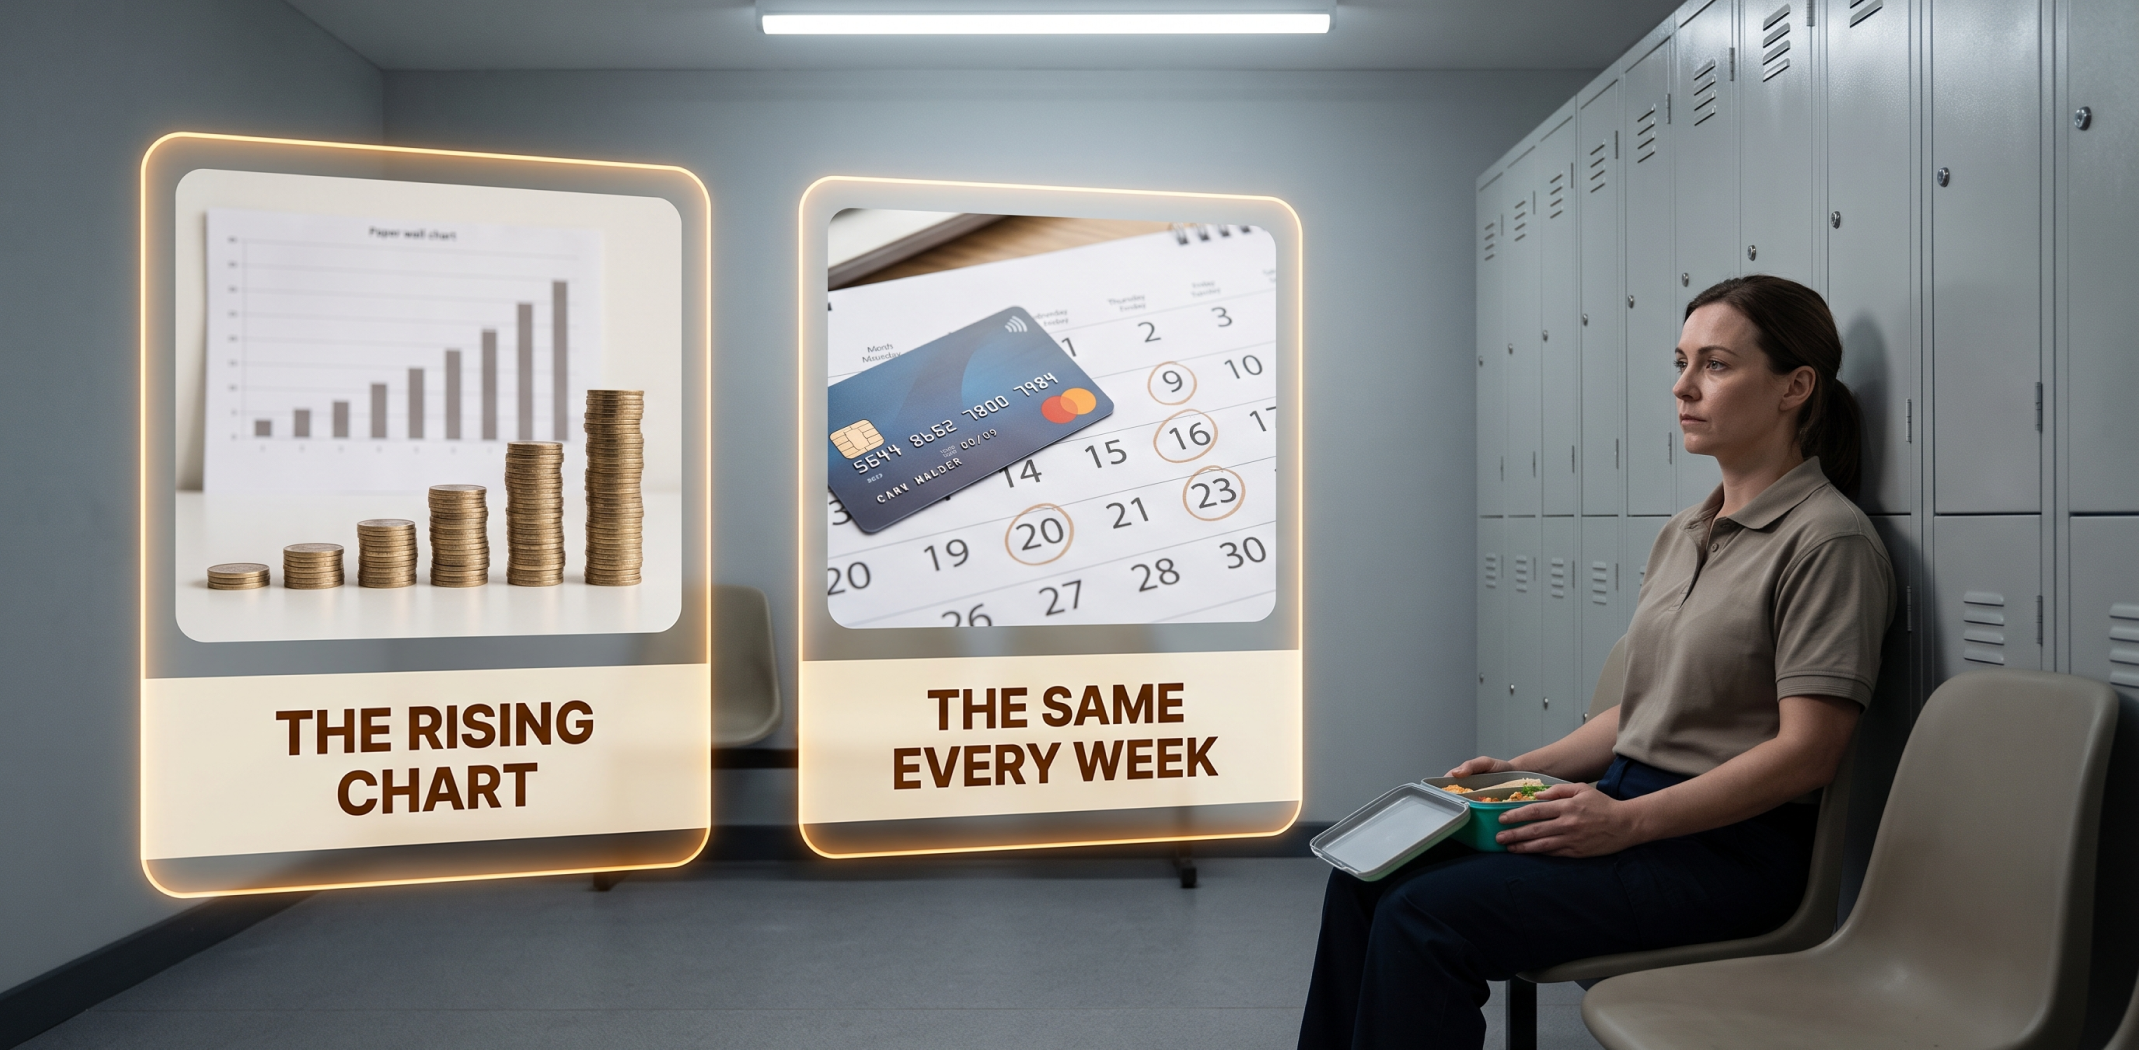
The mechanism is worth seeing plainly. A classic rising challenge saves a small amount in week one and its largest amounts in the final stretch, which means the hardest deposits arrive in the last three months of the year – exactly when heating, gifts and short daylight are already pressing on the same account. A flat transfer spreads the identical total evenly and never asks more of December than of March. Laying both schedules against your own year is usually the moment the argument ends.
So the question is not which method has more discipline behind it. It is whether the biggest week of the plan is smaller than what a bad week can spare.
Match the method to your income
Work out what a poor week looks like for you rather than an average one, then find yourself in the table. Sizing the worst week first takes a few minutes and tends to end the debate on the spot.
| Your income | What usually works | Why |
|---|---|---|
| Same amount every week | A flat transfer usually wins | Nothing to decide, nothing to skip |
| Steady, with a tight season | A flat transfer, or a challenge that peaks early | The rising version breaks in your tight months |
| Tips, shifts or commission | A challenge shaped to your own weeks | You can flex the amount when a week is thin |
| Not sure what a bad week looks like | Work that out first | Every row above depends on it |
Treat those as a starting point rather than a rule. Whether you are paid weekly or monthly, when your bills fall and how much sits in the account before payday all move the line, which is exactly why the answer is yours rather than general.
If it is a challenge, the shape matters more than the total
Here is the part people miss: the total at the end is the least interesting number in a savings challenge. Almost every version reaches roughly the same place. What differs is when it asks for the money, and reordering the weeks to fit your year is what turns an abandoned chart into a finished one.
Three changes tend to be the difference between finishing and quitting.
Same total · three ways to make it survivable
Front-load it, or reverse it entirely. Put the largest deposits in your easiest months and the smallest in the tightest. The total is identical and the failure point disappears.
Match the rhythm to your payday. Weekly deposits on a monthly salary means three weeks of waiting and one of scrambling. Fortnightly and monthly versions exist for a reason.
Build in a skip, on purpose. A plan with two allowed misses survives a bad month. A plan with none gets abandoned the first time life interferes, which is a design flaw rather than a character one.
Same money at the end. The order and the rhythm decide whether you get there.
Notice that none of this asks for more discipline than you already have. It asks for a schedule that was built around your year rather than around a chart somebody printed in January.
Why most challenges break in the same month
Because the classic version was designed to look neat rather than to be finished. Rising deposits make an attractive chart and put maximum pressure on the weeks with the least room. Around week forty the deposits stop feeling like a game, one gets missed, the run is broken, and a broken run is what people abandon – not the saving itself.
The opposite mistake is quieter. A flat transfer set at an optimistic figure fails differently: it goes out on time, the account runs short by the twentieth, and the money comes back out again a week later. That is not saving, it is a round trip. Setting the amount from a poor week rather than a good one is what stops it. Results vary and this is general guidance.
Guess vs challenge vs a plan shaped to you
You can build either version yourself, for free, on a piece of paper. Here is how the usual routes compare with shaping the schedule around your own income.
| Way to decide | Cost | Built on your weeks? | Time |
|---|---|---|---|
| Print a standard chart | Free | No – the same weeks for everyone | Abandoned around week 40 |
| Set a transfer and hope | Free | No – the amount is a guess | Ongoing |
| A budgeting app | $5–15/mo | Sometimes – still needs the figure from you | Ongoing |
| 52-Week Savings Challenge Builder | $9 | Yes – your weeks, your rhythm, your skips | About 15 min |
“Is the whole challenge thing not a gimmick?” The chart is a gimmick and the psychology is not. Visible progress genuinely helps people who have failed at saving quietly, which is most people who try. What deserves the criticism is the standard schedule, not the idea: it asks the most of you in the months that have the least, then treats the resulting miss as a personal failing. A schedule built around your own year keeps the part that works. This is general educational guidance about household saving rather than financial advice.
If it still sounds like a small distinction, two people ran the same total and only one reached the end.
Two people, two very different weeks
One is paid the same amount every Friday. The other has never had two identical weeks in her life.
“I tried the printed chart twice and stopped both times in November. The third year I just set the same amount every week and forgot about it. Boring beat clever by a distance.”
Dane P. · council groundskeeper, Spokane WA
“A fixed transfer bounced twice in my first month because my weeks are nothing alike. What worked was a challenge I could flex, with the big weeks in summer when the tips are good. Same total, finished for the first time.”
Colette M. · bartender, Lubbock TX
If the income itself is the unpredictable part rather than the schedule, the Irregular Income Budget Plan is built for budgeting against a month you cannot forecast. Results vary; this is general guidance rather than financial advice.
Five short answers, and a schedule shaped around your own year comes back the same day, with the biggest deposits moved to the months that can carry them. It is built from what a poor week actually looks like for you rather than from a chart printed for everybody, which is why it tends to survive the point where the printed ones stop. Two skips are built in on purpose.
*Individual results may vary.
Savings challenge or automatic transfer, which is better?
Why do savings challenges fail in the last few months?
Can I run the challenge in reverse?
How much should the automatic transfer be?
What if I miss a week?
Does the rhythm need to match my payday?


Recommended for You