A Second Source Of Income For A One-Paycheck Family, Without A Second Job

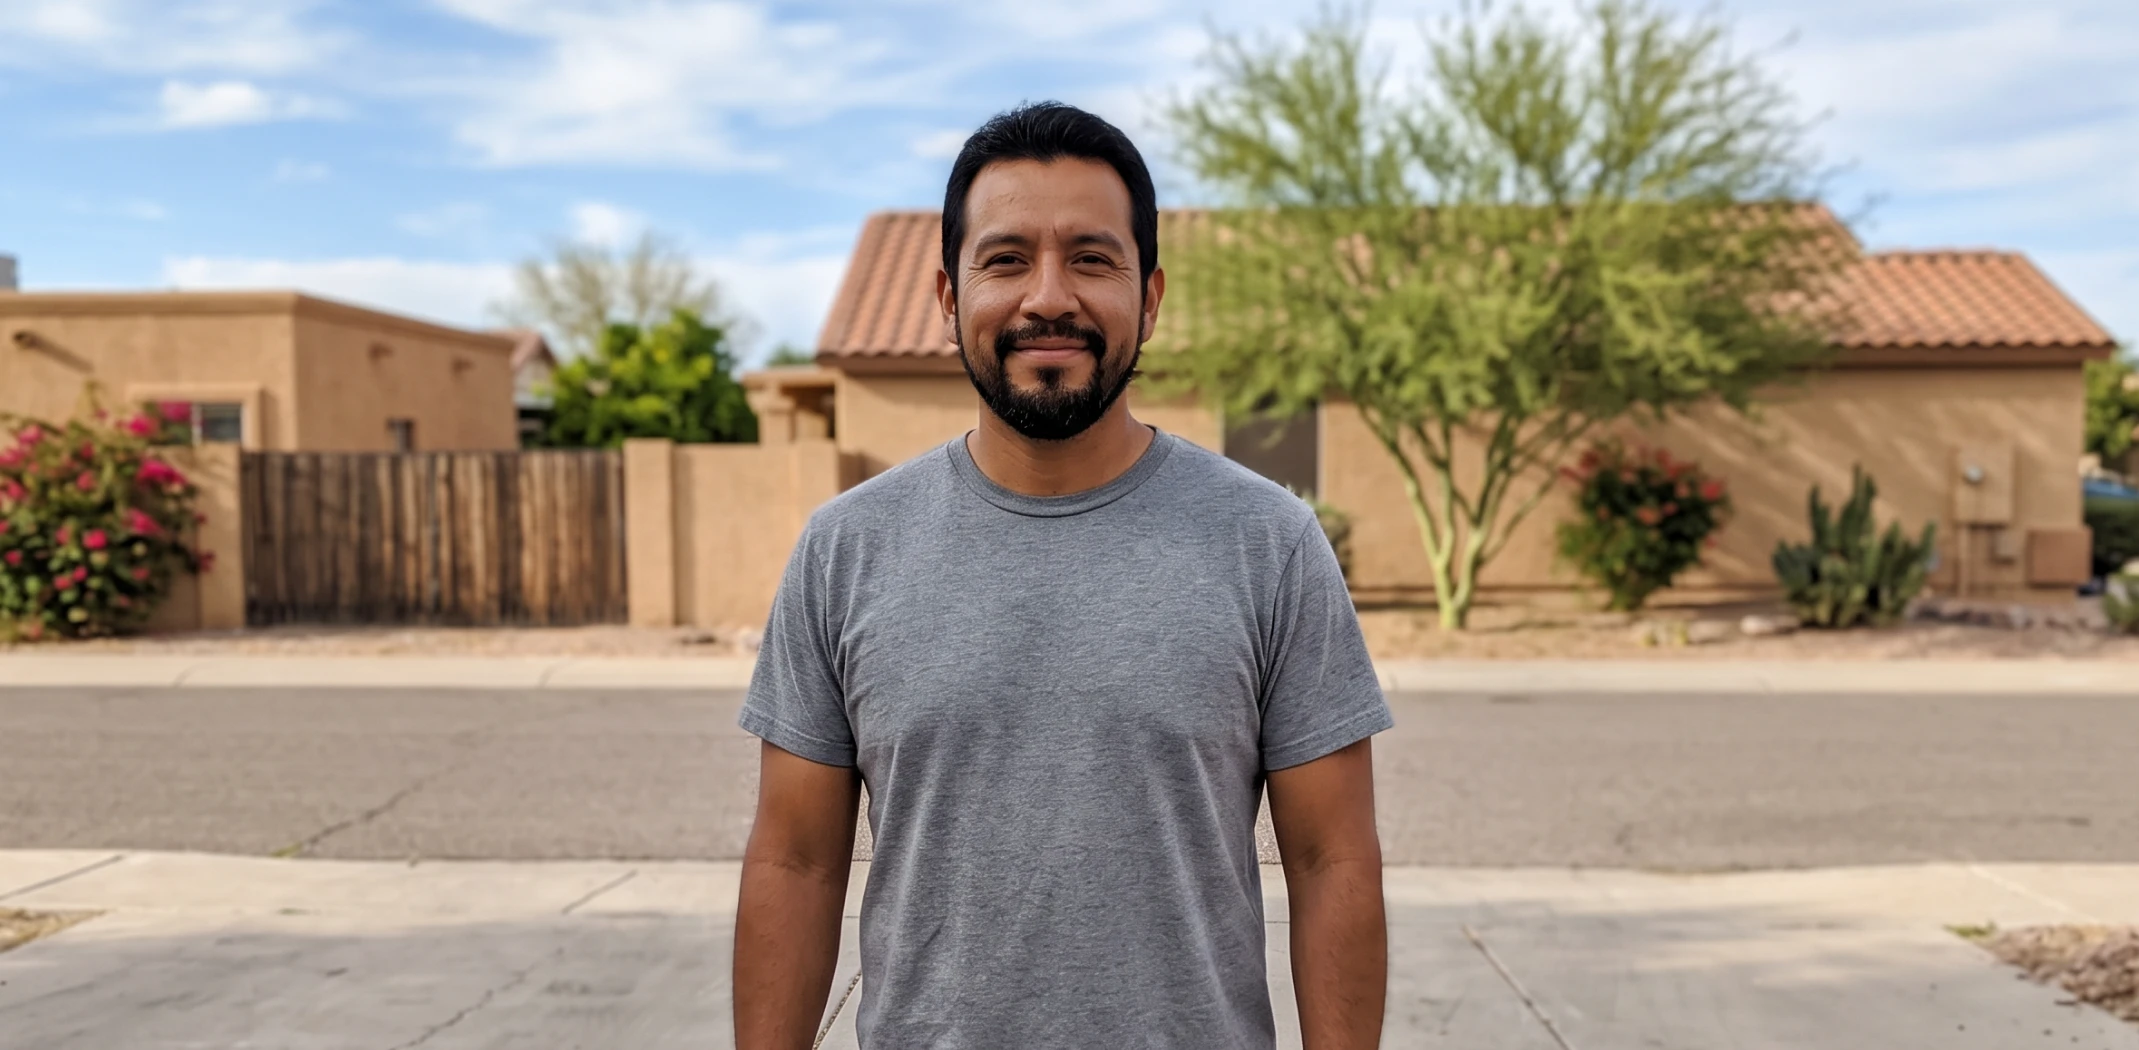
Javier, 41, is a truck dispatcher at a freight company in Albuquerque, New Mexico. His wife stays home with their two kids, ages 1 and 4. Everything the family has depends on one paycheck of about $4,600 a month.
Last spring his company closed another branch and let 30 people go. His job was safe, for now. But that night he did the math. Their savings would cover about one month. One letter from HR, and they would be in trouble by the second.
He had tried a side gig once, driving at night for a month, and quit when he barely saw his kids. He needed something different, not just more hours.
Why a second source of income matters more than a raise
A raise makes one paycheck bigger. It does not make it safer. If that one source stops, everything stops. A second source of income, even a small one, changes the picture: it buys time, it adds to savings, and it proves you can earn outside one employer. Most people skip it because they think it has to mean a second job.
His brother-in-law had done something similar and told him to start with a plan. Javier used an income diversification planner with a skills and assets audit.
Ten questions and an honest risk check
The planner asked ten questions, one at a time. Main income: a full-time job. How secure: somewhat. Savings: about one month of expenses. Top skills: scheduling and logistics, fixing bikes, talking to customers. Things he owns that could earn: a pickup truck and a two-car garage full of tools. Time: about 5 hours a week. Money to start: under $500. Type: a mix of active and passive. Goal: build a safety net. Past side gigs: night driving, quit after a month.
What his plan showed
one income, four people, one month of savings. Not a reason to panic, the plan said, but a reason to start now.
weeks 1–4: small moves and haul-away jobs with his pickup on Saturdays. Low cost, money in the first month.
weeks 5–8: rent half of the garage to a neighbor for storage. Little work once it is set up.
weeks 9–12: bike tune-ups and fixed-up used bikes for spring. Slower to build, but it uses a skill he enjoys.
The plan also had one firm rule: Saturdays and one weeknight only, and a list of burnout warning signs. No more nights away from the kids.
How he built a second source of income in 12 weeks
Weeks 1–4 · The truck – a post in two neighborhood groups: “Pickup and two hands for small moves and haul-away, Saturdays only.” Five jobs in the first month.
Weeks 5–8 · The garage – he cleared one side and rented it to a neighbor storing a boat and tools for $100 a month, with a simple written agreement.
Weeks 9–12 · The bikes – spring tune-ups for neighbors at $40 each and two old bikes fixed and sold. His first $120 from the third stream.
Every Sunday · The tracker – a simple table with each stream and what it earned. All side money went straight to savings.
The garage was the surprise. One afternoon of clearing out, one agreement, and $100 shows up every month while he does nothing.
What changed after three months
Javier still has one job, and he still likes it. But the fear is smaller. He knows that if the job ended, he could earn something the very next Saturday, and the family would have more time to recover.
- Check how many months you could last
- List what you own, not just what you know
- Start with one quick win
- Set fixed hours that protect family time
- Send side income to savings first
- Starting three things at once
- Late-night gigs that wear you out
- Spending side money right away
- Quitting your job too early
- Waiting until a layoff to start
By week 12 his three streams brought in about $580 a month, roughly an eighth of his paycheck. In three months the family added about $1,700 to savings, and for the first time they have more than one month of cushion.
What it costs next to other options
Javier compared a few ways to protect his family. Here is how they look.
| Option | Cost | What you get |
|---|---|---|
| A second part-time job | Your evenings | Steady pay, little time with family |
| Night gig driving | Fuel and wear on your car | Flexible, but tiring and uneven |
| A paid side-income course | $200+ | General ideas, not your skills or assets |
| Income Diversification Planner | $39 | A risk check, a skills and assets audit, 3 ranked streams and a 12-week launch plan |
“Do I have to quit my job to diversify?” No, and the plan warns against it. Most people keep their job and build a second source of income slowly. Only think about leaving when side income has covered three to six months of expenses for a while.
Two more people who added a second income
“I never thought of my spare room as income. The assets list made it obvious. A traveling nurse rents it for three months at a time, and it covers our car payment.”
Marcy T. · school secretary, Sioux Falls SD
“I wanted to start five things and the plan told me to start one. Pressure washing driveways was my quick win. It paid for itself in two weekends, and now I add a second stream.”
Benny O. · warehouse supervisor, Greenville MS
If you want a side hustle that pays well for a few hours a week, see the Low-Effort High-Pay Side Hustle. Results vary, and this is general guidance, not financial or legal advice.
Javier did not need a second job. He needed a second source of income built from what he already had: a truck, a garage and a skill with bikes. Twelve weeks later, one paycheck is no longer the only thing between his family and trouble.
BUILD MY INCOME DIVERSIFICATION PLAN
*Individual results may vary.
What is a good second source of income?
How do I find a second source of income with little time?
Can I earn money from things I already own?
How much should a second income make?
Should I quit my job once side income grows?
How do I avoid burnout with two incomes?


Recommended for You